Factoring is a powerful way for many businesses to speed up their cash flow. But behind every financed invoice lies one key question: will this invoice actually be paid? That’s what factorability is about. It’s one of the most important things a factoring company looks at. It largely decides how much financing is possible, and on what terms.
In this article, you’ll learn what factorability means, how it’s assessed and why it makes the difference between traditional and American-style factoring.

What is factorability?
Factorability is how certain it is that an invoice will be paid, even if the supplier goes bankrupt. The supplier here is the factoring client: the business that has its invoices financed.
In other words: how likely is that business’s customer to keep paying its invoice, even if the supplier is no longer trading?
What makes factorability good or poor?

Good factorability
Factorability is high for businesses that supply standard goods or services that don’t perish. They work from a clear, approved quote. There are no complicated contracts with bonuses, guarantees or other conditions.
It’s important to always have signed proof of delivery, timesheets or CMR consignment notes. These documents prove that the work was actually delivered. That makes it hard for the customer to dispute the invoice.
Poor factorability
Factorability is low for businesses where the value only becomes clear at the end of a project.
A classic example is a software developer. They can invoice in stages, but the software is only usable after final delivery. What if the developer goes bankrupt before the software works? Then the customer has nothing useful from the work done so far. So they have no reason to pay the interim invoices either.
Factorability differs by sector and by business
Every activity has its own factorability profile. Even two businesses in the same sector can differ. It depends on how their order-to-cash process is organised: everything from quote to payment.
Types of factoring and the role of factorability
Factorability in traditional factoring
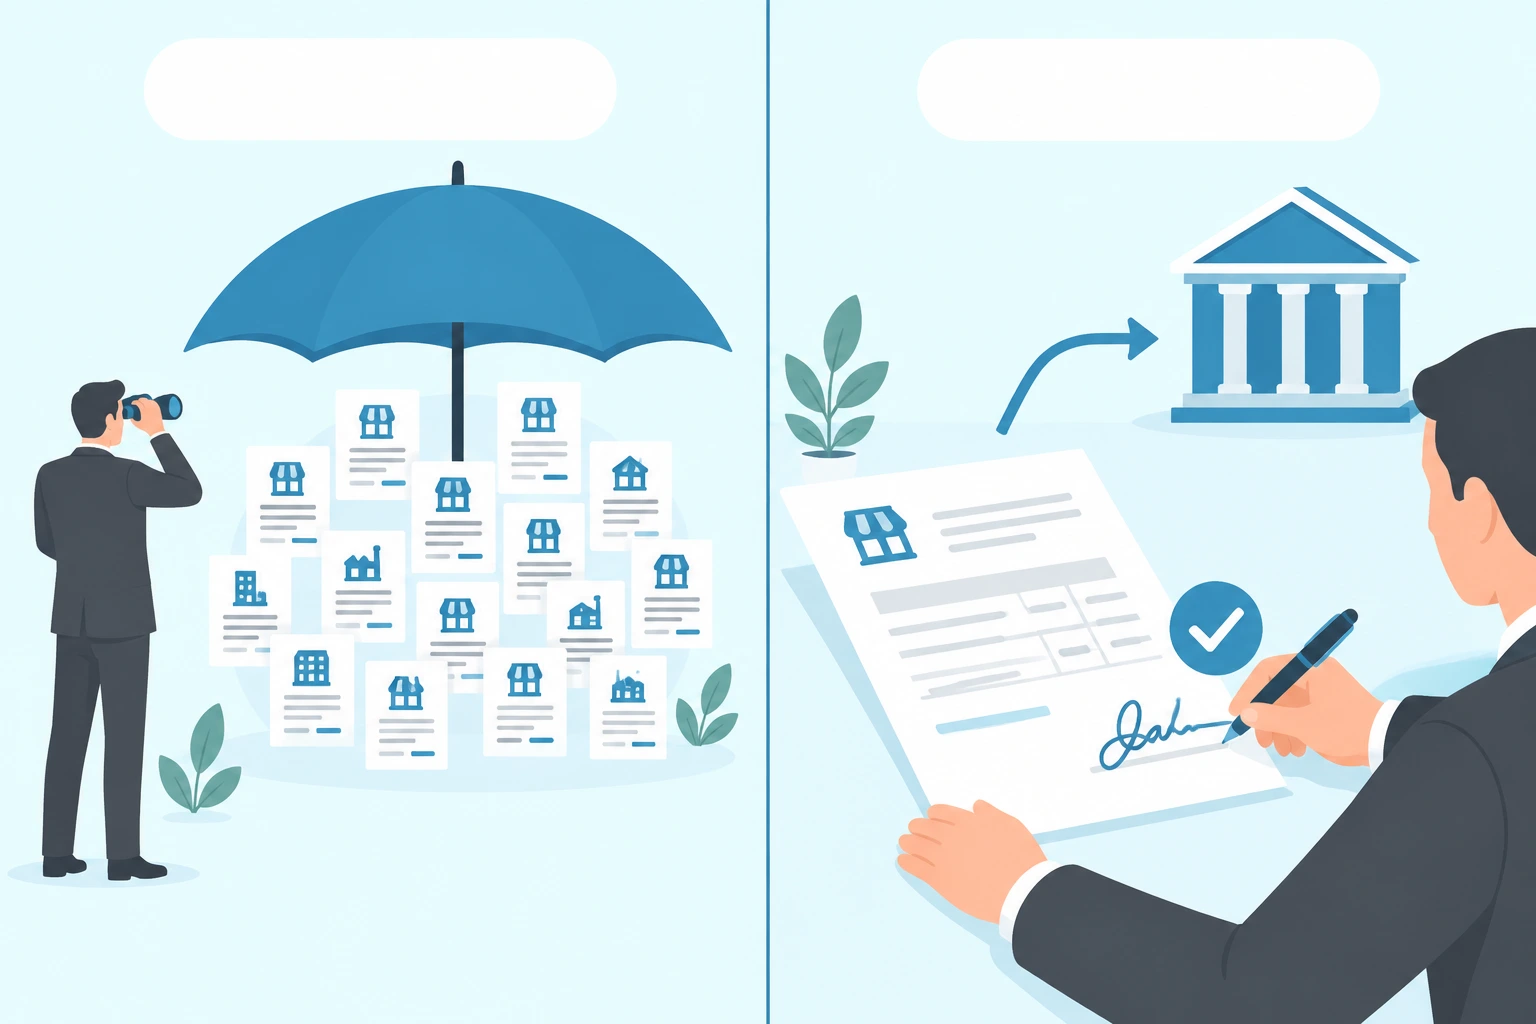
For traditional factoring companies, factorability is everything. They only accept a client if factorability is high enough. They don’t analyse every invoice or every customer contract separately. They rely on good factorability to mean that most invoices will be paid in the end.
Because they don’t know every detail of the contracts, they build in a safety margin. They usually finance 75% to 85% of the invoice amount. That leaves room to absorb unpaid invoices, bonuses or credit notes without a loss.
They also set concentration limits. As a rule, no single customer may make up more than 20% of the total outstanding balance. That way, one unpaid invoice can’t cause them a loss.
American-style factoring: a different focus, a different approach
With American-style factoring, factorability plays a much smaller role. What matters here is how creditworthy the business’s customer is. That customer must also explicitly approve the invoice. And they confirm that they’ll pay on the due date, into the factoring company’s account.
This largely removes the risk of non-payment if the supplier goes bankrupt. These companies can then finance 90% to 100% of the invoice. Concentration on one customer isn’t a problem either. Even a single customer can be enough.
Want to see how big that difference can be in practice? Read our client story: From 40% to 100% financing at Worksgroup.
American-style factoring does need more follow-up from the factoring company. That’s why it’s usually a little more expensive. In return, many more sectors can use factoring, such as construction. In the past, factoring was hard to apply there.
Want to know how to compare the costs of both types? Read our 5 tips for comparing factoring companies.
Frequently asked questions about factorability
Can I improve my factorability?
Often, yes. Use clear quotes, signed proof of delivery and simple contracts without complicated conditions. The better you can prove that you’ve delivered, the higher your factorability.
Is factoring possible in construction?
Yes. With American-style factoring, factoring is now also possible in construction and other project-based sectors. It then mainly depends on how creditworthy your customers are and whether they approve your invoices.
What if one customer makes up a large share of my turnover?
With traditional factoring, that can be a problem because of concentration limits. With American-style factoring, it’s usually not an issue.
Got another question? See all our FAQs.
Factorability: a summary
Factorability largely decides whether, and how, a factoring company is willing to finance your invoices.
- Traditional factoring relies on high factorability. It limits the risk with concentration limits and a lower financing percentage.
- American-style factoring looks at the strength of each transaction on its own. That makes higher financing and more sectors possible.
Thanks to that shift, factoring is no longer limited to businesses with simple products. Complex and project-based sectors can now qualify too.
Factorability isn’t just theory. It decides how much working capital you can free up today. And the difference often lies not in your sector, but in how your contracts, deliveries and invoicing are set up.
Not sure whether your invoices qualify for factoring? Or wondering whether you could free up more cash than you think? Get in touch for an initial chat.
About the author
Peter Hendrix is the founder of Nextfactor. He has worked in factoring for around thirty years. He knows how banks and fintechs work and how their offers differ. At Nextfactor, he helps SMEs find the financing solution that truly fits them.